Part of JV Financial ServicesSEC reporting, bookkeeping & tax → jvfinancials.com
JV Financial ServicesRETIREMENT PLANNING Book a consultation

Retirement planning · Houston and nationwide

Retire with dignity, on a plan built around your taxes.

Most retirement advice ignores the tax return. Ours starts there. Whether you're deciding what to do with a 401(k) or building a pension for your own business, you'll see the options side by side, including fees, access to your money and how each one is taxed, before you decide anything.

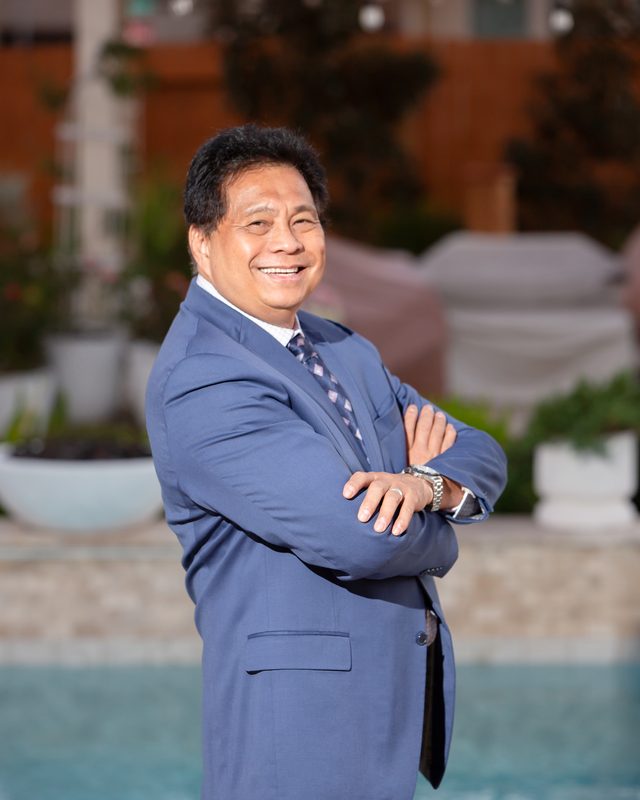
Jorge L. Verar, CPA, CFE, CISA20+ years in tax and financial reportingLicensed Texas insurance agentInsurance placed through Best Financial Partners

For retirees and near-retirees

Your old 401(k): four choices, side by side

There's no single right answer. The right one depends on your age, other savings, how soon you need income and how much market risk you can live with. Here is how the choices compare.

OptionFeesAccess to moneyProtection / guaranteesTaxesWatch for
Leave it in the planFormer employer's 401(k)Plan administration plus fund expensesSet by plan rules; some plans limit partial withdrawalsNone against market loss; ERISA creditor protectionTax-deferred; RMDs applyLimited fund menu; age-55 separation rule may allow earlier penalty-free access
Roll to an IRADirect trustee-to-trusteeFund and account costs; vary widelyFull, subject to tax and the 10% penalty before 59½None against market lossTax-deferred if done as a direct rolloverIndirect rollovers: 20% withholding and a 60-day deadline
Roll to a fixed or indexed annuityHeld as an IRAOften no annual fee on the base contract; optional income riders cost about 0.9–1.5% a yearUsually 10% free withdrawal a year; surrender charges for 5–10 yearsNo loss from market declines; optional lifetime income. Guarantees depend on the insurer's claims-paying abilitySame IRA rules; RMDs applyCaps and participation rates limit upside; long surrender periods
Cash it outNoneImmediateNoneTaxed as ordinary income; 10% penalty before 59½ (some exceptions)20% mandatory withholding; may push you into a higher bracket

Many people combine options, for example keeping part of the money invested for growth and placing part in an annuity for guaranteed income. Annuities are not FDIC insured and are not right for money you may need in the next few years.

Taxes

Roth conversions

Pay tax now at a known rate so future withdrawals, and what you leave your heirs, come out tax-free. We model it against your actual return, year by year.

Required

Required minimum distributions

RMDs start at 73 (75 if born in 1960 or later). Planning a few years ahead can lower the tax bill and Medicare premium surcharges (IRMAA).

Income

Income you can't outlive

Combine Social Security timing, savings and, where it fits, an annuity's lifetime income so your essential bills are covered no matter how long you live.

Protection

Life insurance with living benefits

Coverage that can pay part of the benefit early for a qualifying chronic, critical or terminal illness, while protecting a spouse's income.

Legacy

Leaving money well

Beneficiary designations, the 10-year rule for inherited IRAs, and life insurance as a tax-efficient way to pass money to children.

Peace of mind

Final expense planning

Plan funeral costs ahead with dignity so your family isn't left with the bill or the decisions.

How it works

Strategy first. Products only if they fit.

Discovery

A conversation about your goals, plus a look at your last tax return, statements and existing policies.

Your blueprint

A written plan comparing your options on fees, access, guarantees and taxes. Yours to keep, whether or not you work with us.

Implementation

Rollovers, plan documents with a third-party administrator, and any insurance or annuity applications you choose.

Annual review

We revisit income, RMDs, tax brackets and beneficiaries each year as the rules and your life change.

How we're paid

No surprises

When we recommend an insurance product, Jorge is paid a commission by the insurance company. You'll always see what the product costs you, and you're free to buy it elsewhere or not at all.

Jorge L. Verar

Who you work with

Jorge L. Verar, CPA, CFE, CISA

Jorge has spent more than 20 years on tax returns and financial statements for physicians, business owners and public companies. He's also a licensed insurance agent, so the tax plan and the retirement plan come from the same person instead of two advisors who never talk.

CPA · CFE · CISATax, fraud examination and IT audit credentials
Licensed agentTexas life & annuities, license #3035260
Houston820 Gessner Rd · meetings in person or online

Insurance products are placed through Best Financial Partners, a Houston insurance agency, with carriers including:

National Life GroupAmerican EquityAtheneLafayette Life